Five annuity myths busted
Annuities may seem complicated, but they can help provide financial security in retirement.
In June 2026 we surveyed 2,000 UK adults aged 50 and over and found that misconceptions about annuities remain widespread. In simple terms, annuities are retirement products that turn some or all of your pension savings into a guaranteed income, either for a set period or the rest of your life. However, misunderstandings about how they work sometimes put people off.
That’s where we may be able to help. From concerns about flexibility to confusion over what happens to an annuity when you die, our myth-busting annuity expert Mike Batty is on hand to separate the facts from the fiction.
Key takeways:
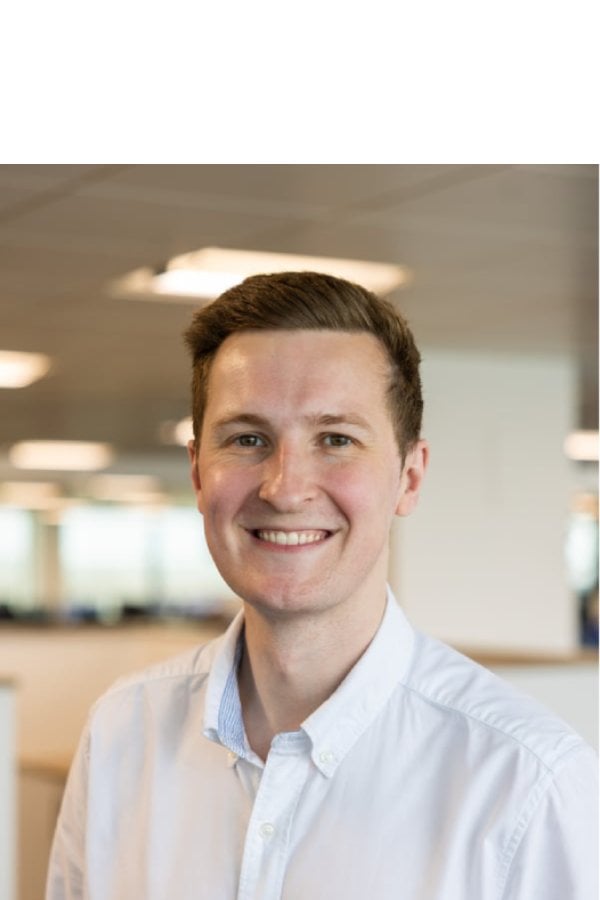
Meet our annuity expert, Mike Batty
Managing Director for Lifetime Mortgages Business & Product & Strategy Director for Retail Retirement
What our survey found: Only 35% of respondents correctly identified a lifetime annuity as the retirement option that guarantees an income for life. More men (43%) knew this than women (28%), while respondents over the age of 55 were more likely to be aware of lifetime annuities than those under 55.
Mike Batty says: A lifetime annuity’s defining feature is security. It can provide an income for the rest of your life. You don’t have to commit your entire pension pot. You can use a part of your pot to buy an annuity and keep the rest invested if you want more flexibility. Your annuity can pay you a monthly income, helping to replace your monthly salary and make budgeting easier.
Bottom line: While an annuity may not suit everyone, it can help provide financial certainty and cover essential spending as part of a wider retirement plan.
Learn more: Watch our Annuities Explained series to find out how annuities work.
What our survey found: While roughly two-thirds of respondents understood the basics of annuities, 30% felt they’re too difficult to understand. Women were more likely to feel unsure, with 34% saying they don’t know enough about annuities, compared to 21% of men.
Mike Batty says: Annuities are actually quite simple. They let you exchange some or all of your pension savings for a guaranteed income. You could buy a lifetime annuity, giving you a guaranteed income for life, or a fixed-term annuity, paying you a guaranteed income for a set period of time, such as five or 10 years, depending on what’s right for you.
Bottom line: Annuities are simpler and more flexible than many people think. However, it’s important to understand that once your annuity is up and running, you can’t make changes to it. That’s why it’s important to choose the right one for you.
Learn more: Discover the different types of annuity we offer.
What our survey found: One in five respondents (20%) incorrectly reported that annuities are purely for retirees, or something to consider after retirement.
Mike Batty says: In fact, you don’t have to wait until retirement to buy an annuity. Some fixed-term plans are available from age 55, potentially helping to ease the transition from working life to retirement.
Bottom line: Fixed-term annuities can be used as a bridging product to help you transition from full-time work to retirement, or until you start receiving a state pension. It’s about choosing the right approach to suit your needs.
Learn more: Explore our fixed-term annuities.
What our survey found: Around 17% of respondents believed that any money in an annuity would be lost when they die. The men we surveyed were more likely to believe this (20%) than women (15%).
Mike Batty says: Many people assume annuity payments automatically stop when they’re no longer here, but this isn’t always the case. Features such as guarantee periods and joint-life options can help provide ongoing support for loved ones.
Bottom line: You can buy an annuity that will continue to pay an income to a loved one after you die. Depending on the features you select, benefits after your death may be paid as continuing income or a lump sum. These features may affect the starting income you receive. This information does not constitute advice.
Learn more: Compare annuity types to find the plan that’s right for you.
What our survey found: About 21% of the people we surveyed said that annuities are expensive. Cost concerns were most prevalent among those under 55 (29%), compared to 19% among those aged 55 and over.
Mike Batty says: The value you get from an annuity depends on your individual circumstances and the retirement income you're looking to secure. An annuity can provide the certainty and financial security that comes with knowing how much income you'll receive in retirement.
Bottom line: For many of us, knowing how much income we’ll receive each month in retirement can provide financial security.
Learn more: View current UK annuity rates.
It’s worth noting that an annuity may not be right for everyone. Once you buy an annuity, you generally cannot change your mind, cancel it or get your lump sum back.
The income it provides may not keep pace with rising prices, unless you choose an inflation-linked option. Additionally, if you want to maintain payments to your loved ones after you’re gone, you must select death benefits when you set up your annuity.
Ready to learn more about annuities?
See the latest annuity rates or use our annuity calculator to explore how much you’d have to spend and what you might get at different ages.
Related articles

Why choose L&G for your annuity?
What is an annuity and how do annuities work?
How much does an annuity cost and how do I buy one?
Need help?
Making well-informed decisions about how to finance your retirement is important so it’s worth shopping around and making use of the guidance and advice services available:
Retirement guidance
Pension Wise from MoneyHelper
The government’s free and impartial service, offering guidance to make money and pension choices clearer for over 50s.
To find out more or book an appointment online click below or call.
0800 138 3944
Monday to Friday, 9am to 5pm.
Calls may be recorded and monitored.
Speak with us
Our colleagues in Cardiff are always happy to answer your questions or tell you about our retirement income products.
Retirement advice
Financial Advice service from L&G
Our advisers are experts in retirement regulated by the Financial Conduct Authority, so you can trust them to provide impartial advice and a personal recommendation that’s right for you.