What are the latest annuity rates?
We live in difficult financial times. The cost of living crisis is hitting us all. But if you’re nearing retirement or already retired, the current economic clouds could have a very important silver lining – annuities.
Once you’ve bought an annuity, it’s a very stable way of funding your retirement. They’re one of the few ways you can get a guaranteed retirement income for the rest of your life. Annuity rates can constantly change but yours will be locked in when you choose to buy your annuity.
What is an annuity rate?
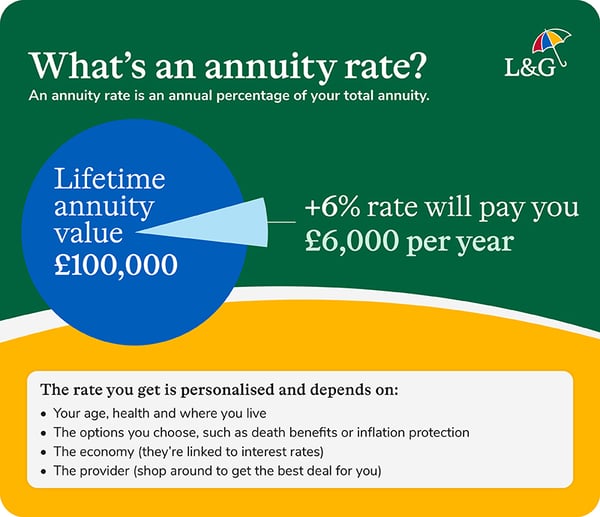
An annuity rate is the measure of how much income you get from your annuity.
Annuity rates are usually given as an annual percentage of the amount your annuity costs. So for example, imagine you spend £100,000 on an annuity. If it has a:
2% rate, it will pay you £2,000 a year
6% rate, it will pay you £6,000 a year
10% rate, it will pay you £10,000 a year
The actual rate you get will depend on several factors, including:
Annuity Calculator
Estimate your guaranteed retirement income in minutes. Use our free pension annuity calculator to see what you could get.
Want to learn more about annuities?
Watch our annuities explained video series and learn more about how annuities work, types of annuity and how to buy an annuity.
What makes annuities so stable?
Once you’ve locked in your annuity rate, the income you’ll get is completely secure. Your annuity will pay out for the rest of your life – so you can live to 100 plus and still get your regular payments. And it will keep paying your agreed amount, whatever happens in the stock market and the wider economy. Though of course, depending on how long you live after buying your annuity, you might get back less than you paid into it.
Why have annuity rates risen?
UK annuity rates have risen over the last few years because they’re closely linked to interest rates. Annuity providers usually buy government bonds to create reliable returns for their customers. When interest rates go up, bond returns rise with them. That boosts annuity rates too.
What impact are current annuity rates having?
Annuities have become much more attractive as pension annuity rates have gone up. That rise means that UK pension savers will get a higher guaranteed income than if they bought an annuity a few years ago. And as at 12 October 2026 our latest annuity rate is 7.36%*.
Though of course other factors, like your age and the size of your pension pot, will also affect the annuity rate you’re offered. You can find out more in our article 'How much does an annuity cost?'
*Based on our average annuity rates at 12 October 2026, and an average premium £70k with various benefits for an average age of 65.
Annuity income by age and lifestyle - based on a pension pot of £100,000
Annuity type | Age 55 | Age 60 | Age 65 | Age 70 | Age 75 |
|---|---|---|---|---|---|
Single life, no health issues | £6,492 | £6,806 | £7,435 | £7,899 | £8,658 |
Joint life, no health issues | £6,130 | £6,501 | £6,843 | £7,379 | £8,021 |
Single life, smoker | £6,740 | £7,090 | £7,767 | £8,299 | £9,111 |
Joint life, 1st life smoker/2nd life no health issues | £6,264 | £6,658 | £7,024 | £7,610 | £8,298 |
Single life, no health issues. RPI (inflation-linked annuity) | £3,969 | £4,428 | £5,022 | £5,560 | £6,516 |
Joint life, no health issues. RPI (inflation-linked annuity) | £3,659 | £4,027 | £4,484 | £5,114 | £5,794 |
Single life, smoker. RPI (inflation-linked annuity) | £4,205 | £4,699 | £5,336 | £5,940 | £6,964 |
Joint life, 1st life smoker/2nd life no health issues. RPI (inflation-linked annuity) | £3,783 | £4,170 | £4,650 | £5,328 | £6,054 |
You'll notice that joint life annuities generally provide a lower starting income than single life annuities. That's because they can continue making payments to a partner or dependant after your death. Learn more about joint life annuity options and how payments work.
All income is for a lifetime annuity that has a Guaranteed Minimum Payment Period for 10 years. Annuity income for a smoker is based on a person smoking 10 cigarettes a day. Annuity income correct as at September 2026.
What are the best annuity rates in the UK?
To find the best pension annuity rates, UK savers should compare the market and see what’s currently available. You can visit the award-winning Annuity Ready website to compare rates across the whole market. We’ll also compare the annuity market for you, and show you the best income you could get, even if it’s not with us.
Annuity rates are linked to interest rates, so when interest rates go up, annuity providers generally start offering better deals. They’ll also look at your age, health and other personal circumstances. Any product choices you make (like setting up payments to your partner after your death) can also affect the rate they offer you.
Is an annuity right for me?
An annuity could be right for you if you want a guaranteed income in retirement. To buy a pension annuity, you'll normally need to be aged 55 or over and have at least £10,000 in your pension pot.
An annuity may be worth considering if you:
When should I buy an annuity?
Annuity rates have risen in recent years, but there's no guarantee they'll remain high. The best time to buy will depend on your personal circumstances, retirement plans and income needs.
You don't have to choose one option
It's not always an either/or decision. Some people use part of their pension pot to buy an annuity for guaranteed income and keep the remainder invested in drawdown for flexibility.
Important things to consider
Before buying an annuity, think about:
- how annuity income could affect your tax position
- whether it could impact any means-tested benefits
- the options you want, such as inflation protection or payments to a loved one after death
Remember: annuities are usually irreversible
Once your cancellation period has ended, you generally can't:
- change your annuity
- cash it in
- surrender it
Choosing the right provider
When comparing annuities, it's worth considering more than just the rate. Factors such as service, financial strength and ongoing retirement support may also be important. Discover why customers choose L&G for their retirement income needs.
Get guidance before making a decision
It's important to choose the right annuity and set it up in the best way for your circumstances. Shop around, compare providers and consider seeking professional financial advice.
What should I do next?
If you’re nearing retirement and not sure if an annuity’s right for you, or how to get the best out of your pension pot more generally, Pension Wise can help. It’s a free government guidance service from MoneyHelper.
To find an independent financial adviser of your own, visit the Unbiased website. Once you’ve found the right one, you’ll probably have to pay for their advice. We also offer a Retirement Advice service for over 55s.
And if you’re not sure how much to save, the Retirement Living Standards website will help you see how much different retirement lifestyles might cost. Then you can use our own Retirement Income Calculator to see how much you might need to save to achieve that level of income.
Ready to get an annuity quote?
We can put together a personalised annuity quote for you, which will tell you if you could get a better rate elsewhere.
FAQs
The best annuity isn't always the one with the highest starting income. The right option will depend on your personal circumstances and the features that matter most to you. For example, options such as joint life cover, inflation protection and guarantee periods can affect the income you receive while providing additional financial security for you or your loved ones.
You can also learn more about the different options available in our guide to comparing annuities.
Joint life annuities typically provide a lower starting income because they can continue paying an income to a surviving spouse, partner or dependant after the first person dies. The level of income will depend on factors such as age, health and the options chosen, but the additional ongoing cover generally reduces the initial income available.
Find out more about how joint life annuities work and how payments continue after death.
A good annuity rate depends on your age, health, pension value and the options you choose. Because rates vary between providers and can change over time, it's important to compare personalised quotes rather than focus on a single headline rate.
You can learn more about the factors that affect annuity income in our how much does an annuity cost guide.
Related articles
Compare annuities: Should I buy one?
How much does an annuity cost and how do I buy one?