How much does an annuity cost and how do I buy one?
Annuities give you a guaranteed retirement income for the rest of your life.
-
If you’re looking to purchase an annuity, you’re probably wondering how much they could cost and how you actual buying one. We’ve put together this page to help you.
-
If you're new to annuities, we’d recommend starting with our guide to what an annuity is before digging into annuity cost and purchase details.
How much does an annuity cost?
When you’re buying an annuity, you have to spend at least £10,000. How much you might spend beyond that depends on a wide range of factors. The most important ones are:
- Your pension pot size: It goes without saying that the more money you’ve saved up, the more you can spend when you come to buy an annuity.
- How old and healthy you are: As a rule, the older you are the better annuity rate you’ll get. You might also get a better one if you’re facing certain health issues.
- The type of annuity you choose: You’ll get different rates with different products and providers. Any features or benefits you choose might also affect the price you pay.
- Market annuity rates: They affect the deals your provider offers. In general, if they’re higher you’ll get a better deal and if they’re lower you won’t.
Want to learn more about how your annuity is calculated?
Watch our annuities explained video series and learn more about how annuities work, types of annuity and how to buy an annuity.
You can see our latest annuity rates or use our annuity calculator to explore how much you’d have to spend and what you might get at different ages.
Annuity cost examples
See how much different annuity spends could get you if you:
- buy your annuity when you’re 65
- take your 25% tax-free cash then spend the rest of your pot on an annuity
- want a guaranteed income paid monthly for the rest of your life
- want a 10-year guaranteed minimum payment period
- don’t go for any extra product options or benefits
- are in perfect health
| Your pension pot size | Your tax-free cash lump sum | Your pre-tax annual annuity income |
| £50,000 | £12,500 | £2,325 |
| £250,000 | £62,500 | £12,180 |
| £500,000 | £125,000 | £24,060 |
| £750,000 | £187,500 | £36,040 |
| £1,000,000 | £250,000 | £48,070 |
| £1,073,100 | £268,275* | £51,480 |
* Tax-free cash is normally 25% of your pension pot, up to a maximum of £268,275. Pension savings above this level won't increase your tax-free cash entitlement.
We used our annuity calculator to create these buying annuities estimates on 28 August 2026. They’re really just a starting point, to give you a general idea of how much annuities cost and the income you could receive.
You can use our calculator to see how much you could get with other amounts of money, or a larger or smaller pension pot. It will also help you explore how different types of annuity could work for you.
Want to learn more about buying an annuity?
Watch our annuities explained video series and learn more about how annuities work, types of annuity and how to buy an annuity.
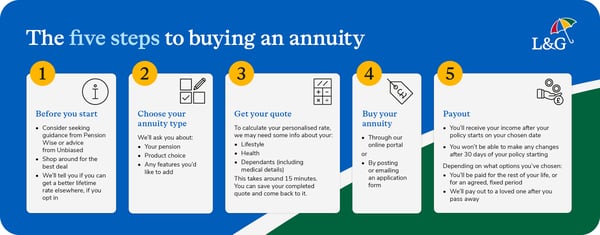
The five steps to buying an annuity
Annuities provide a guaranteed income, but they grow and pay out in different ways. Follow these five steps to find the right plan and secure your retirement income:
FAQs
Yes. You may be able to buy an annuity using cash savings rather than a pension pot. Whether this is the right option depends on your circumstances, tax position and retirement goals. If you’re not sure, we’d recommend chatting with a financial adviser.
Yes, you can buy an annuity without a pension. But that may or may not be a good idea. It depends on a variety of other factors, like where you’ve saved your non-pension cash and what else you could do with it. If you’re not sure, we’d recommend chatting with a financial adviser.
Yes. While many people buy an annuity using their pension savings, you can also use other types of savings or cash. Whether this is right for you depends on your circumstances, tax position and retirement goals. If you're unsure, consider speaking to a financial adviser.
The right annuity for you will depend on your retirement income needs, health, age and personal circumstances. You should consider factors such as whether you want payments to increase over time, provide benefits to a loved one after your death, or include a guaranteed payment period.
It's important to choose carefully, as you can't normally change an annuity once it's been set up. If you're unsure which option is right for you, consider comparing providers and seeking financial advice.
You can buy an annuity directly from a provider or through a financial adviser. A good first step is to get a quote and compare your options. Before making a decision, it's worth shopping around to see what different providers offer.
Yes. You don't have to use your entire pension pot to buy an annuity. Some people use part of their pension to secure a guaranteed income and keep the rest invested or take it in other ways, depending on their retirement plans.
No, you can’t change your annuity once you’ve bought it. But you can opt for annuities that change in a pre-agreed way. For example, you could set up your payments to rise in line with inflation or have them transfer to a loved one after you die.
There’s no right or wrong time for buying an annuity. UK savers probably won’t need the guaranteed income an annuity gives them until they start working part time or stop working entirely. It could be better to wait, because providers usually offer better rates as you grow older.
That’s up to you! You might want the security of a guaranteed income as soon as you’re old enough or you may want to wait a bit for a better deal. If you’re not sure, talk to an adviser.
If you delay buying your annuity, you’ll have to wait longer for your guaranteed income to kick in. But you’ll probably get a better rate when you do buy it. That’s because providers offer older buyers better annuity rates. If you’re not sure when’s best, ask a financial adviser.
Yes, you'll need at least £10,000 to buy an annuity after taking your tax-free cash. If you want to take your 25% tax-free cash out of your pot before you buy your annuity, the minimum amount you’ll need in your pot is £13,333.
You'll also need to be aged 55 or over, although the minimum pension age is due to increase to 57 from 6 April 2028.
When choosing an annuity, it's important to consider your income needs, retirement plans, age and personal circumstances. Once you've bought an annuity, you can't make changes to it, so it's important to choose the right option for your needs.
Yes. Different providers may offer different annuity rates, features and benefits. Comparing quotes can help you find the option that's most suitable for your needs.
Related articles
Compare annuities: Should I buy one?
What are the latest annuity rates?