Women climbing

Personal Pension

A personal pension designed to fit your life

Pay in when it suits you, get tax relief and choose how your pension is invested.

Flexible ways to save for retirement

Our Personal Pension helps you plan for today, tomorrow and later life. Whether you're starting out or bringing pensions together, you can:

  • Save regularly or make one-off contributions
  • Get tax relief on what you pay in
  • Choose a ready-made option or take a more hands-on approach
  • Access our drawdown and annuity options when you're ready to retire

We look after you with expertise and support at every stage. We're recognised as the UK's most admired financial services company1 and we manage more savings and investments than any other firm in the UK2.

Flexible retirement savings

Save for your long-term future with a personal pension that works alongside your State and workplace pensions.

Your pension, you're in control

You can set it up yourself. Start with £100, add lump sums or regular payments when it suits you. You can even transfer in other pension pots.

Simple options, managed for you

You can choose from simple, ready-made or risk-based options. Our experts manage your investments for you.

Boosted by tax relief

You could get up to 25% added to your contributions through government tax relief. This helps your savings grow3.

A personal pension could be right for you if:

  • You want flexibility - choose how much you save and change, stop or restart contribtions when your circumstances change.
  • You're self-employed, don'e have a workplace pension, or want to save more for retirement alongside one. Tax relief from the government can boost the amount you save.
  • You have more than one pension - bringing pensions together could make them easier to manage.
  • You want a tax-efficient way to save - your contributions can benefit from tax relief.
  • You're saving for later life - you're happy to leave your money invested until you can usually access it from age 55 (rising to 57 from April 2028)

A personal pension isn't right for everyone. The value of investments can go down as well as up, and transferring or investing in pensions isn't always the best option for your situation. You may want to consider financial advice before you decide.

What are the risks?

A personal pension isn't right for everyone.

  • The value of investments can go down as well as up, and you could get back less than you put in. 
  • Transferring or investing in pensions isn't always the best option for your situation.
  • Tax rules may change, and any tax benefits depend on your personal circumstances.
  • You may want to consider financial advice before you decide.

We don't give recommendations or offer advice. If you're unsure, check out our pensions explained article and videos on pension savings. You can also seek financial advice.

How a personal pension works

Open or transfer in

Start your pension with at least £100, or bring your existing pension pots together in one place.

Choose how your savings are invested

You can choose from simple, ready-made options based on your preferred level of risk.

Pay in and build your savings

Make regular or one-off contributions. Government tax relief can add to what you pay in, helping your savings grow.

Access in later life

Take money from your pension from age 55 (rising to 57 from 2028), with flexible options for how you use it. Our retirement options include drawdown if you want flexibility and annuities if you're looking for a guaranteed income.

For more information, please read our Key Features and Terms and Conditions before you apply. Once you read them, opening your account only takes a few minutes.

Why 12.4 million customers trust us

UK-based support team

Award-winning customer service from our Cardiff contact centre1.

Easy to use app

We're rated 4.8/5 on Apple and 4.8/5 on Google Play2.

Trustworthy

We're the UK's most admired financial services company3.

190 years' experience

We've been helping people build financial security since 1836.

UK no.1 asset manager

We look after over £1 trillion of pensions and investments - more than any other UK company4.

FSCS protected

Your savings are protected by the Financial Services Compensation Scheme (FSCS) up to £85,0005.

Choose a personal pension investment option

Select one option to open your personal pension.

Pick your risk level

For customers who want to invest based on their risk level.

Choose from a small range of ready-made, diversified funds. Each fund matches a different level of risk. Our experts manage the investments for you.

Life-Stage Investing Plan

For customers who don't want to choose their own investments.

We automatically invest your pension in a diversified mix. It aims for growth when you're further from retirement, then gradually moves to lower-risk assets as you get closer, to help protect your savings.

Self-Select Fund

For experienced investors.

Choose a single fund from our wider range. This is for people who want to make their own investment choices.

Transfer and combine your pensions

If you want to bring all your pensions together in one place, you can combine pensions from another provider into one pot with our Personal Pension. It's a low-cost way to keep everything together and easier to manage.

What are the tax benefits of a personal pension?

The tax relief you get, and any tax you may need to pay, depend on your individual circumstances. These rules can change in the future.

What are the tax benefits of a personal pension?

The tax relief you get, and any tax you may need to pay, depend on your individual circumstances. These rules can change in the future.

Tax relief for you

When you pay into a pension, the government adds tax relief to your contributions. This helps your savings grow faster.

Tax-efficient pension growth

Any income or gains in your pension are usually tax-free.

Personal Pension fees and charges

Breakdown

A clear breakdown of our fees, so you know what you're paying.

  • Service charge: 0.25% - deducted monthly
  • Fund charges: 0.31% - deducted annually

What you'll pay in fees

If you invest £1,000, you'd pay around £5.60 in fees over a year. 

That's less than the price of two cups of coffee6.

Get support your way

When serving our customers, we offer the best of both worlds.
Contact centre call agent laughing while talking to a customer

Talk to a person in our UK contact centre

Our Cardiff contact centre team is specially trained to help with your enquiry. Calls may be recorded and monitored. 

In March 2026 we proudly won the Trusted Quality Provider Award from the Institute of Customer Service. 
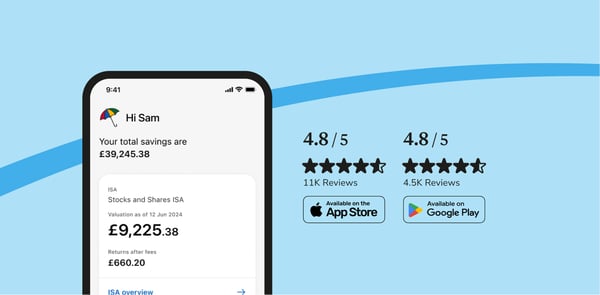
Latest app rating in app downloads

Self-serve with our top-rated app

"The L&G app is fantastic! The interface is clean, modern, and very easy to navigate, making it a pain-free experience... The team has done a great job of making financial management simple and engaging. Highly recommended!" 

App user review

Pensions explained

New to pensions? We answer some key questions you might have before you start saving for retirement.

Pension videos

Watch our pensions explained video series and learn more about how pension savings work, how much you should put in your pension and everything you need to know about pension consolidation.

Be investor safe

Scams are often smart, sophisticated and hard to spot. So we've created a pay to help you protect yourself from fraud.

Common questions about personal pensions

Find out more about private pension (UK) savings and our Personal Pension with our frequently asked questions.

A pension is a good way of building up a pot of money to live on when you may no longer work.

If you can wait until you’re at least 55 (rising to 57 from April 2028) to access your savings and you’re comfortable making your own decisions, a personal pension might work for you.

A personal pension should not be considered as a replacement for a workplace pension, if you have access to one, as your employer will also make contributions.

However, a personal pension is an important savings tool if a workplace scheme is not an option or you want to supplement your workplace pension savings.

If you want the option to withdraw your money before you’re 55 (rising to 57 from April 2028), an ISA may be a better option.

Our Personal Pension may be right for you if:

  • You are self-employed.
  • You need flexibility.
  • You are looking to consolidate your pension pot.
  • You are happy to choose from a small range of funds based on your attitude to risk or a default investment option if you don't want to select your investments.

Our Personal Pension may not be right for you if:

  • You already have a workplace pension, which satisfies your retirement goals.
  • You have a limited company and want to contribute from your business.
  • You are looking to invest in multiple funds or a wide choice of investment funds, specific equities or property funds.

Most people can pay up to £60,000 per year in pensions without incurring a tax charge. This is called your Annual Allowance. The exact amount you can pay will depend on your total annual income.

You can find out more about the tax rules for pensions here. And you can see how much could be in your pension pot when you choose to retire with our pension calculator.

It’s important to save for retirement, so whilst you don't have to regularly pay money into your Personal Pension, it's a good idea to do so.

With our Personal Pension you can:

  • Set up regular payments.
  • Pay in one-off lump sums.
  • Start, stop or amend your regular payments to suit your needs.

No. Our Personal Pension is set up for you to contribute into. Your employer should be contributing into a Workplace Pension on your behalf.

Find out more about the different types of pensions.

Yes, we accept transfers into a L&G Personal Pension. When you transfer your pension, the current provider will sell your investments and send us the proceeds, which we will invest in your chosen fund with us. We cannot take control of your existing investments.

Your current pension provider may apply exit penalties if you close your pension pot. You could also forfeit some other benefits or guarantees if you decide to transfer, so it’s best to check the terms of your existing pension first.

There are also some types of pension we can't consolidate, such as 'final salary' plans, With Profits plans and those with Guaranteed Annuity Rates or Guaranteed Minimum Benefits.

If you're unsure if a pension is right for you, get in touch with a financial adviser or find one through Unbiased.

We offer a range of ready-made funds spanning five different risk profiles. All you need to do is select the level of risk you’re willing to take and we do the rest, spreading the money you’ve chosen to invest in the fund across different investments.

These can include a combination of markets, industries and asset types. This means you can confidently make your own decisions without having to worry about the underlying investments yourself.

If you do not want to make your own investment choice, we provide a default investment option. This option automatically changes investment funds over time, as you get closer to your selected retirement date.

You can find the relevant investment information on our site and in each fund’s factsheet or Key Investor Information document.

You have the right to change your mind within 30 days of your pension being set up. This cancellation date will be shown in your welcome email.

To cancel, please log in to your online account and send us a secure message. You’ll get your money back and won’t have to pay any charges.

However, the amount you get back may be less than you invested if the value of the fund has decreased. If you don’t cancel within 30 days, you can still stop paying money in.

Your current savings will remain invested and charges will apply.

To find out more about opting out of your pension, read our article ‘Can I opt out of my pension?’.

Yes, you can transfer your pension to another company. Please speak to your new pension provider so you can follow their process.

With a personal pension, your investments are managed for you. But with a SIPP, you get full control over your investments. You can either manage them yourself or ask an adviser to manage them for you. To find out more about SIPPs, visit our What is a SIPP? article.

[1]  Source: britainsmostadmired.com in partnership with London Stock Exchange

[2] Sources: L&G £1.177 trillion global assets under management as at 31 December 2025 and Top 200 fund managers in Europe by global AUM

[3]  Source: 8k reviews on Apple App Store and 4k reviews on Google Play Store

[4]  Source: britainsmostadmired.com in partnership with London Stock Exchange

[5]  Sources: L&G £1.177 trillion global assets under management as at 31 December

[6] Full details in terms and conditions

[7] Source: Google, 30 June 2026