
Building more through collaboration
By Carolyn Thornley-Yates, Commercial Director, Chorley Building Society
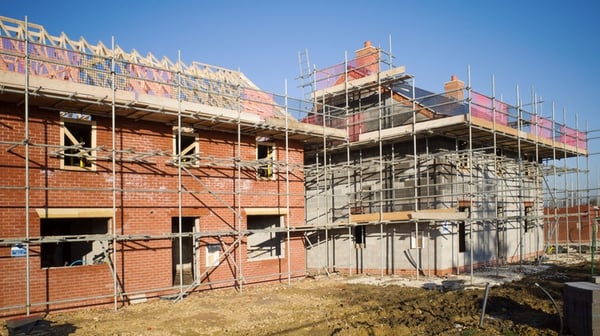
For a smaller building society, new build and self build present a real opportunity to do what mutuals do best: understand individual circumstances, take a more flexible approach and support customers whose needs may not fit neatly within an automated lending model.
But succeeding in these markets is not something lenders can, or should, do alone. Collaboration across the industry is key. Bringing together lenders, brokers, developers and specialist service providers allows each party to contribute its expertise and ultimately create better solutions for customers.
Self build is a great example. Working with specialists such as BuildLoan gives societies access to expertise around project costs, cashflow, build monitoring and stage payments. BuildLoan itself recognises that there is no one-size-fits-all funding solution for self builders. Similarly, in the new-build market, initiatives such as Own
New demonstrate what can be achieved when lenders, entrepreneurs and the wider housebuilding industry work together.
Regulators also have an important role in enabling innovation. A significant development for building societies has been the Prudential Regulation Authority's decision to remove SS20/15, the supervisory statement governing building societies' treasury and lending activities.
The PRA recognised that its prescriptive expectations could limit societies' ability to compete and grow, while risk management within the sector has become more sophisticated.
Removing those constraints gives societies greater scope to determine their own risk appetite and consider how they can support areas such as new build and self build, while continuing to lend responsibly.
The Building Societies Association has similarly argued that removing SS20/15 enables societies to tailor their risk-management frameworks to their own business models.
There is a strong customer case too.
For buyers concerned about affordability and the overall cost of home ownership, a new-build property can offer greater certainty and reduce the immediate risk of unexpected maintenance and improvement expenditure.
For smaller societies, our strength lies in manual underwriting, bespoke solutions and the ability to look at the individual story behind an application. Combine that with specialist partnerships and a regulatory environment that allows societies greater flexibility, and smaller lenders can make a meaningful contribution to financing the new homes Britain needs.