
Why new builds appeal to buy-to-let investors
By Martin Sims, Distribution Director, Molo Finance
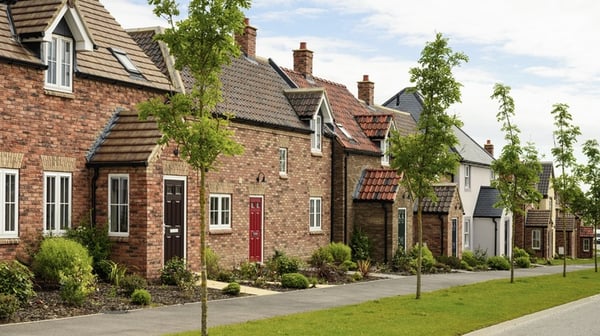
A new-build buy-to-let can offer a landlord a turnkey purchase, with the interior finished to an agreed specification and energy efficiency built into the home. The appeal is practical. They can budget for a property where the fittings are new and, once it is complete, prepare for the first tenancy with little initial work. As their broker, you can help investors assess how the purchase fits their investment plans and arrange the borrowing around the developer’s timetable.
A fresh start for the landlord and tenant
Part of the appeal comes down to how much a landlord knows about the property from the outset. The heating system is new, and the developer can provide specifications for the fixtures and fittings. Having that information to hand makes it easier to plan maintenance and understand the warranties that come with the home.
There is also an opportunity to choose a finish that suits the intended tenants.
Depending on the developer and the stage of construction, buyers may be able to select flooring or other fittings before completion. A landlord expecting longer tenancies might favour durable materials that will stand up well to everyday use.
Agreeing the specification early means the home can arrive with those choices already in place.
Tenants, meanwhile, have the prospect of being the first to make the space their own. A newly fitted kitchen and a bathroom nobody else has used can be persuasive at a viewing. Combined with a layout that suits how they live, the finish can help them picture staying beyond their first tenancy.
Energy efficiency benefits
The attraction continues once tenants move in and start paying the bills. Modern insulation and efficient heating can make a home more comfortable without requiring as much energy to keep it warm.
The Home Builders Federation’s 2026 Watt a Save report, produced with Octopus Energy, found that 87% of new-build EPC registrations in its analysis were rated A or B. Its comparison of 90-square-metre homes put annual energy costs for A- and B-rated properties around £421 below a D-rated equivalent.
A tenant comparing two homes will be thinking about what they can afford each month, including the bills alongside the rent. Lower expected energy costs give them another reason to consider the property. The landlord may also have less energy improvement work to budget for, with efficiency built into the home at construction.
Finding a home that fits the rental market
Having several layouts to consider in a new-build development means the landlord can think about the type of tenant they want and choose accordingly. An apartment with room for a desk, for example, could appeal to someone who works from home several days a week, while a larger home would potentially suit a family.
The surrounding area helps complete the picture, with a nearby station likely to draw commuters, while access to outdoor space could appeal to families looking for a longer-term home. Speaking to local letting agents can help your client understand which features tenants ask for and what comparable properties are achieving in rent.
Having local knowledge also puts the developer’s rental projection into context. Your client can assess the purchase with a clearer idea of demand, allowing for ongoing costs such as service charges where applicable. A well-chosen property should suit the people likely to rent it as well as the landlord buying it.
Buying ahead with an off-plan property
Some clients will want a completed home they can view before buying. Others may prefer to reserve off-plan, securing their chosen property while construction is still under way. Buying earlier can offer more choice within a development and time to prepare for the eventual letting.
The mortgage conversation needs to reflect the longer lead time, as a developer may ask for exchange shortly after reservation, with completion expected months later. Establishing both dates early on helps you arrange the borrowing around the purchase. Check how long the mortgage offer will remain valid and what an extension would involve if the handover date changed.
Your client should also confirm what is included in the agreed finish, so they can budget for any additions they want. A handover inspection provides an opportunity to identify snagging and agree any follow-up with the developer before the tenancy begins.
Supporting new-build purchases with Molo
At Molo, new builds form part of our buy-to-let range. We offer lending up to 75% LTV, with two- and five-year fixed options available to individuals and limited companies, subject to criteria.
Speak to our BDM team about your client’s plans and the anticipated completion date. We can discuss the property’s eligibility and any developer incentives before you submit the application, helping you arrange a mortgage that supports the purchase.